Feeling drained by credit card debt? Here’s why personal loans are becoming the go-to solution
Carrying credit card debt with an APR over 22% can really weigh you down. Discover how personal loans might help reduce your expenses, what interest rates are like following the latest Fed increase, and the best timing to make the switch.
Beware: minimum payments keep you trapped in debt
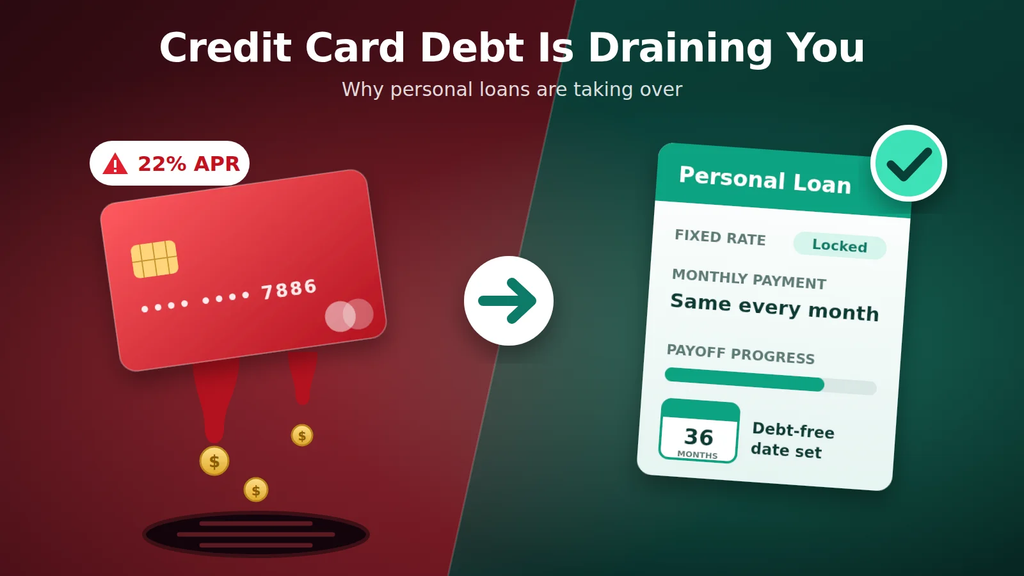
Credit card debt is sapping your finances, and it’s not just a feeling.
If your September credit card bill included back-to-school expenses on top of a balance that never seems to shrink, you’re far from alone.
According to the Federal Reserve Bank of New York, Americans now carry $1.263 trillion in credit card debt.
The consequence: millions of borrowers are quietly shifting their credit card debt into personal loans.
Personal loans offer fixed interest rates, set monthly payments, and a clear payoff date. Here’s what’s driving this trend, the data behind it, and how to decide if it’s right for you.
H2: Why Credit Card Debt Is Sapping Your Finances Today
According to the Federal Reserve’s most recent report, the average APR for credit cards that charge interest stands at 22.15%. Your rate will vary based on your credit score. For example, WalletHub notes that new card offers average 27.01% for fair credit and 23.27% for good credit.
With an APR of 22.15%, carrying an average balance of $7,886 means you’re paying roughly $146 per month just in interest. This is money that doesn’t reduce your principal at all.
The September Fed rate hike only adds fuel to the fire
The FOMC unanimously voted 12–0 to increase the federal funds rate to a range of 3.75%–4.00%.
Fed Chair Kevin Warsh stated that “inflation remains too high and has persisted for far too long.” Inflation currently stands at 3.4%, with 16 out of 18 officials anticipating at least one more rate hike before the end of the year.
The majority of credit cards carry variable APRs linked to the prime rate, so rate increases impact you immediately.
Ted Rossman, former lead analyst at Bankrate, notes that Fed rate adjustments “typically reach consumers within one to two months” and influence both existing and new balances.
Back-to-school expenses have arrived
Spending from August is now appearing on September credit card bills. According to a NerdWallet survey, 19% of parents expect to carry credit card debt due to back-to-school expenses, while 24% plan to rely on Buy Now, Pay Later options.
An Increasing Number of People Are Falling Behind
The New York Fed reports that the percentage of credit card balances becoming seriously delinquent (over 90 days late) climbed to 6.97% in the second quarter of 2026.
Joelle Scally, Economic Policy Advisor at the New York Fed, cautioned that “new delinquencies on auto loans and credit cards remain persistently high.”
How Much Could You Save by Making the Switch?
Can consolidating your debt improve your credit score?
Yes, it often does. According to a study by TransUnion, 68% of people who consolidated their debts saw their credit scores improve by over 20 points.
Average credit card balances decreased from $14,015 down to $5,855. “Debt consolidation loans tend to achieve what they’re meant to,” said Liz Pagel, former Senior Vice President at TransUnion.
Is a Personal Loan the Right Choice for You?
When a personal loan fits your needs
- Your new loan’s APR is significantly lower than your credit card’s APR, including fees;
- You can comfortably manage the fixed monthly payments;
- You’re determined to avoid racking up credit card debt again after paying off;
- Your credit score is at least 690, qualifying you for better rates.
Be Aware of These Potential Risks
- Origination fees: some lenders subtract these upfront, so compare the APR not just interest rates;
- Fair or poor credit: average rates between 23.73% and 27.27% might not be better than your card;
- Increasing delinquencies: personal loan late payments (60+ days) rose to 3.81%. Only borrow what you can repay;
- Don’t rely on a rate limit: the suggested 10% cap on credit card interest isn’t law yet. Waiting for it might cost you valuable interest savings.
How to Convert Credit Card Debt to a Personal Loan in 5 Simple Steps
Step 1: Write Down All Card Balances and Their APRs
Before contacting any lender, make sure you have a clear picture of what you owe and the cost. Grab your latest statement for each card and note down:
Find the “Interest Charge” section on each statement. This is the amount you pay monthly that doesn’t reduce your principal balance at all.
The average outstanding balance stands at $7,886, with an APR averaging 22.15%. This means interest alone costs about $146 per month.
Step 2: Check Your Credit Score for Free
Your credit score has the greatest impact on the interest rate you’ll qualify for. The gap between credit tiers can be significant:
Source: NerdWallet, September 2026.
Most banks and credit card issuers provide free access to your credit score.
To get your full credit reports, visit AnnualCreditReport.com, the official website offering free weekly reports from Equifax, Experian, and TransUnion.
Step 3: Prequalify with a Minimum of Three Lenders
Prequalifying lets you see your estimated interest rate, loan amount, and monthly payments without impacting your credit score, since lenders perform a soft credit check.
A hard credit check only occurs when you submit a formal loan application.
Be sure to compare at least one lender from each of these groups:
- Online lenders: fast decisions, often with funding in days, and easy online prequalification;
- Banks: may offer lower rates if you’re already a customer. The Fed reports 11.86% as the average on 24-month bank personal loans;
- Credit unions: federal credit unions are generally limited to an 18% APR ceiling. That makes them a strong option if your credit isn’t perfect.
Pro tip: seek out lenders that provide “direct pay to creditors” options. This means funds go straight to your credit card companies, bypassing your checking account entirely.
Step 4: Evaluate APR, Fees, and Overall Loan Cost
The advertised rate often doesn’t tell the whole story. Be sure to assess these factors when comparing offers:
- APR vs. interest rate: APR includes origination fees, showing your real yearly expense;
- Origination fee: some lenders deduct this upfront. For example: a 5% fee means borrowing about $8,301 to get $7,886 to pay off your cards;
- Loan length: longer terms reduce monthly payments but increase total costs;
- Prepayment fees: confirm you can pay off early without penalties.
To illustrate, here’s how the loan term impacts the cost for $7,886 at 19.55% APR:
H3: Step 5: Settle Your Credit Cards Immediately and Enable Autopay
As soon as your loan is funded, take action on the very same day:
- Pay every card balance in full. If your lender offered direct pay, confirm the payments went through;
- Check each card account a few days later to confirm a $0 balance. Interest charged in the last cycle can leave a small leftover amount;
- Set up autopay on the new loan so you never miss a payment. Some lenders also give a small rate discount for autopay;
- Keep your card accounts open. Closing them can hurt your score by increasing your credit utilization and shortening your credit history.
Paying off your cards immediately lowers your credit utilization ratio, which is one of the quickest ways to boost your credit score.
A TransUnion report revealed that 68% of consumers who consolidated their debt gained over 20 points on their credit scores.
Step 6: Safeguard Your Progress to Prevent Debt from Returning
This is where many stumble. Paying off credit cards with a loan only helps if you keep those card balances at zero.
If not, you risk ending up with twice the debt.
- Take your cards out of your wallet and remove saved cards from online stores and apps;
- Plan ahead for the holidays. Holiday shopping is weeks away, so set a cash budget now, before the season starts;
- Build a small emergency fund, even $500 to $1,000. Most people rack up card debt again because of an unexpected expense, like a car repair or a medical bill;
- Turn on spending alerts in your card apps so any new charge shows up right away;
- Use your cards for one small bill only, such as a streaming service on autopay. That keeps the account active without letting a balance build up.
Author’s Perspective
Having reported on personal finance for over ten years, I can confidently say this period feels unique.
Credit card balances are at all-time highs, with APRs exceeding 22%, and the Fed has just raised rates instead of lowering them.
Families carrying debt feel pressure from every angle. I’ve seen too many hold out for rate cuts or regulatory limits, while their monthly interest quietly drains hundreds of dollars.
Personal loans aren’t a cure-all and don’t suit everyone. If your credit is mediocre or poor, the numbers might not add up, and consulting a credit counselor could be a wiser first step.
However, if you can secure a significantly lower fixed rate, locking it in before the next rate increase is one of the smartest moves you can make this season.
Recommended Content
Your flood coverage might expire this month
Understand what happens after a coverage gap, details on the NFIP renewal period, and key points to review beforehand.
Continue reading * You will remain on the current site