Mortgage rates climb past 7% again: essential steps for homebuyers today
Mortgage rates have climbed back over the 7% mark. Find out the reasons behind this increase, what it means for your monthly payments, and the best steps for homebuyers moving forward.
Mortgage rates continue to rise: what homebuyers might face
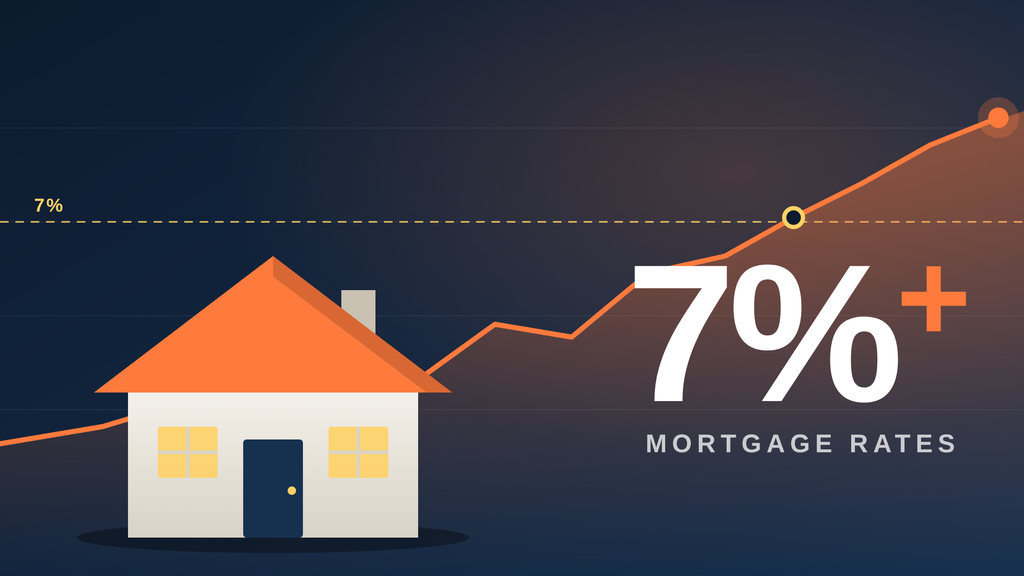
Mortgage rates are climbing once more, making the journey to homeownership costlier for buyers nationwide.
In October 2026, the average 30-year fixed mortgage rate hit 7.40%, increasing the financial burden on families already challenged by high housing costs.
With home prices staying elevated, ongoing inflation squeezing household budgets, and rising borrowing expenses, monthly mortgage payments are becoming tougher to handle.
Even those buyers with steady incomes and strong credit scores may find their borrowing capacity lower than anticipated.
Knowing why mortgage rates are increasing, how much extra you might pay, and what steps to take before applying for a loan can help you avoid expensive mistakes.
Before submitting an offer on a home, here’s what every buyer should understand and do right now.
What’s Driving Mortgage Rates Above 7% Again?
Mortgage rates have risen past 7% once more due to a mix of inflation worries, changes in the bond market, and doubts about the overall economic outlook.
Freddie Mac reports that the average rate for a 30-year fixed mortgage hit 7.40% on October 8, 2026.
It later dropped slightly to 7.24% on October 29 but stayed above the 7% mark.
This is important because mortgage rates affect how much buyers can afford to borrow and the portion of their income spent on housing.
Several economic reasons contribute to the rise.
How Inflation and Treasury Yields Impact Rates
Inflation remains a key driver behind the cost of borrowing over the long term.
In September 2026, the Consumer Price Index (CPI) rose by 0.6% compared to the previous month, pushing the annual inflation rate to 3.7%, according to data from the U.S. Bureau of Labor Statistics.
Energy costs were a key driver of this rise, with gasoline prices climbing 9.1% over the course of the month.
Increases in energy expenses impact transportation, household budgets, and can also shape overall inflation expectations.
When investors worry that inflation will stay high, they tend to seek higher returns on their long-term investments.
A key reference point in this context is the 10-year U.S. Treasury yield.
Mortgage rates aren’t directly linked to this yield, but both are shaped by market expectations of inflation, economic growth, and future interest rate trends.
How the Federal Reserve’s Latest Decision Affects Homebuyers
The Federal Reserve’s moves on monetary policy often shape expectations throughout the financial markets.
That said, these decisions don’t directly control mortgage interest rates.
On October 28, 2026, the Federal Open Market Committee (FOMC) chose to keep the federal funds rate target steady between 3.75% and 4.00%.
The Federal Reserve also noted that inflation levels remain high.
For buyers, it’s key to understand that the federal funds rate mostly impacts short-term borrowing costs.
On the other hand, 30-year mortgage rates are influenced by long-term market trends and expectations.
That’s why a reduction in the Fed’s rate doesn’t necessarily lead to lower mortgage costs.
Rather than depending solely on Fed announcements, homebuyers should track Freddie Mac’s weekly mortgage rate updates and get fresh quotes from lenders.
The Effects of Rising Mortgage Rates on Buyers
An increase in mortgage rates might seem minor when viewed as a simple percentage change.
Still, over the course of a 30-year loan, even a one-point rise in the rate can greatly affect the total cost a borrower ends up paying.
This effect is especially significant for buyers taking out larger loans.
Why It’s Becoming Tougher to Afford a Home
Rising borrowing expenses are just one piece of the challenge.
The high cost of homes and the scarcity of available listings also affect how much buyers must pay.
Per the National Association of REALTORS® (NAR), the median price for existing homes sold hit $417,500 in September 2026.
This marked a 1.3% rise compared to September 2025.
While existing-home sales grew 1.5% from the previous month, they still remained 2.2% lower than a year earlier.
The available housing inventory was about 1.60 million units, which equals roughly 4.8 months of supply.
This situation makes it challenging for buyers who rely on financing.
Although a home’s listing price might appear reasonable, higher mortgage rates can raise monthly payments enough to push it beyond the buyer’s affordability.
For those purchasing their first home, this could lead to:
- Delaying the decision to buy a home.
- Opting for smaller residences.
- Exploring more affordable neighborhoods.
- Building savings for a bigger down payment.
For homeowners considering a move, rising rates can make it tougher to justify swapping out an older mortgage for a costlier new loan.
Steps Homebuyers Should Take When Mortgage Rates Are Above 7%
Mortgage rates exceeding 7% don’t mean buyers must give up on their homeownership goals.
That said, it does require a more thoughtful approach to managing finances before buying a home.
Instead of just looking at the headline interest rate, buyers should consider the overall expenses tied to financing.
Below are practical actions to take before finalizing your mortgage contract.
Shop Around: Compare Offers from Multiple Mortgage Lenders
A key step is to gather mortgage quotes from a variety of lenders and financial institutions.
Mortgage lenders, banks, and credit unions often present different interest rates, fees, and loan terms—even for borrowers with similar credit and income.
The Consumer Financial Protection Bureau (CFPB) advises that reviewing Loan Estimates side-by-side helps buyers spot key differences and negotiate better mortgage conditions.
The CFPB also notes that lenders typically must deliver a Loan Estimate within three business days after receiving the six essential pieces of information needed to process an application.
When selecting a lender, be sure to compare:
- Interest rate: The percentage charged on the borrowed amount.
- APR (Annual Percentage Rate): A broader measure of borrowing costs that includes the interest rate and certain loan-related charges.
- Loan term: Whether the mortgage lasts 15, 20, or 30 years.
- Closing costs: Fees required to complete the transaction.
- Discount points: Upfront payments that may reduce the interest rate.
- Monthly payment: The amount due each month, considering the costs included in the estimate.
A mortgage with a lower advertised interest rate isn’t always the best option.
For instance, a lender might offer a reduced rate but require higher upfront discount points or increased closing fees.
Another lender might present a slightly higher rate but with lower upfront fees.
It’s important to evaluate the overall financial effect, not just the advertised interest rate.
Boost Your Credit Score Before You Apply
Your credit rating affects the mortgage rates and loan conditions you can access.
Lenders typically review credit data to judge the likelihood that a borrower will repay the loan.
Having a stronger credit history can boost your chances of securing better loan terms.
Consider these actions before submitting your mortgage application:
- Verify your credit reports for any errors.
- Always pay your bills promptly to avoid late payments.
- Lower your credit card balances when you can.
- Don’t open multiple new credit accounts before applying.
- Assess your current debts and monthly expenses.
It’s key to realize that mortgage credit score requirements vary and there isn’t a universal minimum.
Different loan types—like conventional, FHA, or VA—each have their own credit criteria.
Buyers should inquire with lenders about which credit scoring model and criteria are used for the mortgage product they’re interested in.
Enhancing your credit profile might take some time, but it can improve your chances of securing better financing terms.
Think About Making a Larger Down Payment
Putting down a bigger down payment lowers the loan amount you’ll need to take out.
This can reduce your monthly payments for principal and interest.
For instance, buying a $400,000 property involves:
- 10% down payment: $40,000, resulting in a $360,000 loan.
- 20% down payment: $80,000, resulting in a $320,000 loan.
Reducing the loan amount can have a significant impact, especially when rates top 7%.
Putting down a larger sum might also help some conventional borrowers avoid paying private mortgage insurance (PMI), which is typically required if the loan-to-value ratio goes over 80%, depending on loan conditions and program rules.
Still, making a bigger down payment isn’t always the smartest choice.
Buyers should refrain from using all their savings to lower the mortgage amount.
Keeping an emergency fund is crucial, especially to cover unexpected repairs, rising insurance costs, or other household expenses.
A sensible down payment should help make mortgage payments manageable without putting the buyer’s financial security at risk.
Understand Rate Locks and Mortgage Points
With mortgage rates fluctuating, buyers might want to secure a fixed interest rate before closing.
A mortgage rate lock is a contract that safeguards the borrower from interest rate hikes for a set period, as long as the loan closes within that timeframe and there are no significant changes to the application affecting the terms.
The CFPB notes that rate locks usually last for 30, 45, or 60 days, though some lenders may offer longer locking periods.
Before you agree to a rate lock, make sure to ask your lender:
- How long will the rate remain locked?
- Is there a fee to lock the rate?
- What happens if closing is delayed?
- Can the rate be adjusted if market rates fall?
- How much would an extension cost?
Another strategy to consider is buying mortgage discount points.
These are fees paid upfront to the lender in return for a chance to secure a lower interest rate.
That said, the actual benefit depends on how much the rate drops and the length of time the borrower keeps the loan.
For instance, if a buyer expects to sell or refinance within a few years, they might not recoup the initial cost of the discount points.
Be sure to weigh the upfront expense against the possible long-term savings before deciding to buy points.
Author’s Perspective
Mortgage rates climbing back above 7% is a significant signal for anyone looking to buy a home in the U.S.
However, the biggest error buyers often make is reacting to headlines without fully assessing their personal financial circumstances.
Taking out a mortgage is a long-term decision, and the interest rate is just one aspect to consider carefully.
Before finalizing a loan, it’s crucial to factor in property taxes, insurance, upkeep, HOA dues, closing fees, and keeping an emergency fund.
With the average rate for a 30-year fixed mortgage now at 7.40% and median home prices around $417,500, affordability challenges are mounting for buyers.
Here’s my straightforward advice: don’t let worries about rising rates push you into a mortgage payment that strains your budget.
Make sure to shop around with various lenders, fully understand all fees, and assess your monthly housing costs before committing to a purchase.
The ideal moment to buy a home isn’t always when mortgage rates hit their lowest levels.
Instead, it’s when the purchase matches your financial situation and ensures you can stay financially stable after moving in.
Recommended content
Why savings rates may finally climb again
Learn what the Fed’s decisions mean for your money and how to compare high-yield savings accounts.
Continue Reading * You will remain on the current site