Reasons behind the rising annual fees on your card
Wondering why your credit card’s annual fee keeps going up? Discover the reasons behind these hikes and find out how to determine if your card remains a good deal for you.
Is your credit card costing more? Beware of rising annual fees
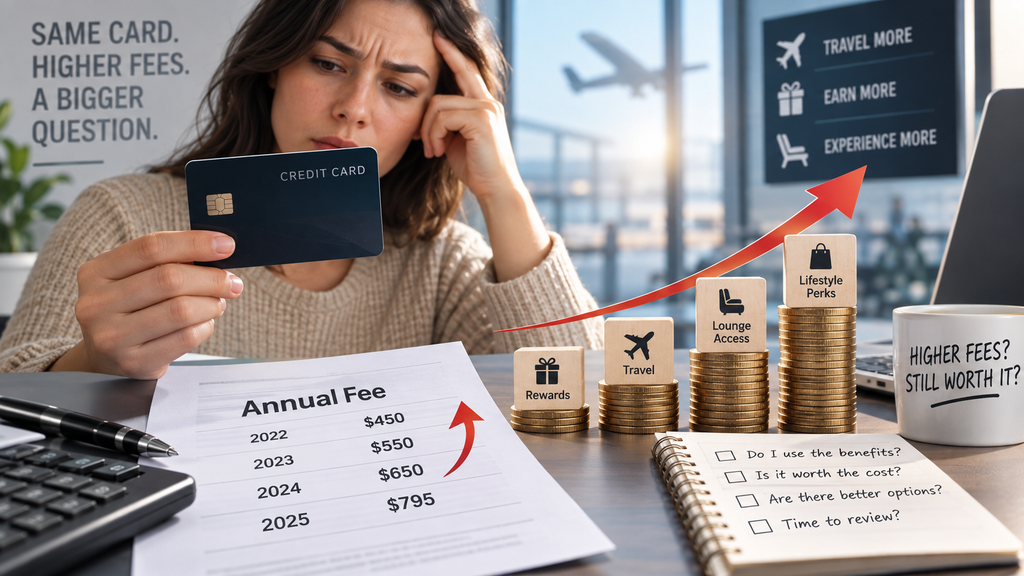
Your credit card’s annual fee might be climbing as issuers boost prices on premium rewards, add travel and lifestyle perks, tweak card economics, and target higher-spending customers with new offerings.
An increased fee doesn’t necessarily mean the card is a better or worse value.
The crucial point is whether the perks you actually use justify the higher annual charge.
What Makes My Credit Card’s Annual Fee Go Up?
A credit card’s annual fee may rise when the issuer updates the card’s pricing structure or adjusts its benefits.
Premium credit cards have increasingly added perks like travel credits, lounge access, enhanced rewards, and lifestyle benefits while also raising their annual fees.
For instance, some recent changes to premium cards have pushed annual fees close to or beyond $800 annually.
The key difference lies between the value the issuer promotes and the actual value you gain personally.
What Causes Credit Card Annual Fees to Go Up?
Common reasons include the following:
- Added travel credits
- Broader airport lounge access
- Increased rewards rates
- New perks for hotels or dining
- Extra statement credits
- Modifications to rewards programs
- Rising costs for premium rewards
- Targeting higher-spending customers
Are Annual Fees on Credit Cards Increasing Across the Industry?
Fee hikes have been especially noticeable among premium credit cards.
The Federal Reserve Bank of New York noted that U.S. credit card debt hit $1.26 trillion in Q2 2026, highlighting the ongoing role of credit cards in managing household finances.
At the high end of the market, certain credit cards now impose annual fees of several hundred dollars, with some products nearing or surpassing $800 per year.
What’s Driving the Increase in Premium Credit Card Annual Fees?
Premium credit cards are increasingly competing by bundling together a range of travel and lifestyle perks.
So, a higher fee often reflects a pricier package of benefits, but having more perks doesn’t always translate into greater value for every cardholder.
How Travel Credits Can Shrink the Impact of a Steep Annual Fee
Imagine a card with a $795 annual fee that offers $300 in travel credits.
The straightforward math is: $795 − $300 = $495
However, that $300 is only truly valuable if you would have spent the same amount on qualifying purchases anyway.
Using just $150 of the credit means your real benefit is nearer to $150, not the full $300.
This difference is crucial when assessing the true worth of premium cards.
The Value of Airport Lounge Access Varies Among Different Travelers
Access to airport lounges can offer real benefits for those who travel often.
If you fly multiple times annually, having lounge access might save you money by replacing expenses you’d normally have at the airport.
But if you seldom travel by air, that same lounge access is likely to hold little meaningful value for you.
Rather than judging a benefit by its listed price, consider how much money it actually saves you.
Rewards Are Only Worthwhile When They Align With Your Spending Habits
A better rewards rate can help justify an annual fee if it applies to the purchases you already make regularly.
However, increasing your spending just to earn rewards often undermines the benefit.
For instance, if a card gives extra points on dining, it doesn’t mean that an unnecessary $500 restaurant expense is actually saving you money.
Rewards should reflect your existing spending patterns, not drive you to spend more.
Is It Worth Keeping a Credit Card After Its Annual Fee Goes Up?
Before deciding to keep, downgrade, or close your card, consider several important factors.
Look at How It Compares to No-Annual-Fee Cards
Don’t limit your comparison just to other premium credit cards.
Evaluate its net yearly worth against cards with no annual fee.
Check With Your Issuer About Switching Products
Before you decide to close your card, find out if your issuer offers the option to switch to a different card.
Depending on your issuer and account type, you might be eligible to switch to a card with a lower or no annual fee.
This option varies from one issuer to another.
Is It Legal for Credit Card Companies to Raise Your Annual Fee?
In general, federal regulations allow certain annual or monthly maintenance fees to increase after the first year, as long as the issuer complies with required procedures.
Regulation Z along with CFPB guidelines set the standards for notifying consumers about specific changes in credit card terms.
Certain modifications require at least 45 days’ advance notice, though the exact rules vary depending on the nature of the change.
What Is the Required Notice Period From a Credit Card Issuer?
When changes fall under Regulation Z rules, cardholders typically receive advance notification.
The notice must provide key details such as:
- The updated fee amount
- The date changes begin
- The affected account terms
- Your rights and options
Be sure to carefully review the issuer’s notice, as rules can vary by fee type and account.
Is It Possible to Avoid Paying a Credit Card Annual Fee?
In some cases, yes. Your choices might include:
- Switch to a no-fee card from the same issuer;
- Inquire about possible product changes;
- Compare your card with others on the market;
- Reach out to the issuer regarding retention offers;
- Cancel the card, keeping credit impacts in mind.
Will Closing a Credit Card Impact Your Credit Score?
Shutting down a credit card can influence elements that affect your credit score.
An especially important factor is credit utilization.
How Should You Handle Carrying a Credit Card Balance?
If you carry a balance month after month, focusing only on the annual fee misses the bigger picture.
According to the Federal Reserve Bank of New York, U.S. credit card debt reached $1.26 trillion in the second quarter of 2026.
For those carrying revolving debt, the interest charges usually outweigh any gains from rewards optimization.
Should You Spend More to Offset an Annual Fee?
Never base financial decisions on spending extra money you wouldn’t have spent otherwise.
When a card has a $500 yearly fee, spending thousands more just to earn rewards may actually raise your costs instead of lowering them.
The objective isn’t to rack up enough rewards to make extra spending worthwhile.
Instead, the aim is to get the most value from purchases you already intend to make.
Author’s Perspective
A rising credit card annual fee calls for a fresh look at your costs, especially when the increase reaches several hundred dollars.
What matters isn’t just if your issuer added perks, but whether those perks align with how you actually spend, travel, and use your card.
When you’re already using the credits and rewards offered, the higher fee might be balanced out by benefits you would have bought anyway.
If you don’t take advantage of those perks, the stated value can be misleading for your own finances.
The easiest way to judge is to ask: how much did I actually save over the past year, and what was my total cost for the card?
That figure provides a clearer view than relying on the advertised value of each perk or bonus.
If you carry a balance, keep in mind that prioritizing rewards only makes sense after you fully grasp your interest expenses.
Recommended Content
Health insurance
Health insurance options may change. Learn why premiums could rise, insurers may exit markets and how to prepare.
Continue reading * You will remain on the current site