Loan Rates: Don’t Miss the Crucial September 30 Deadline
Discover how making automatic payments by the September 30 deadline can help reduce interest rates on qualifying federal student loans.
Is Your Loan Rate Too High? What to Do Before September 30
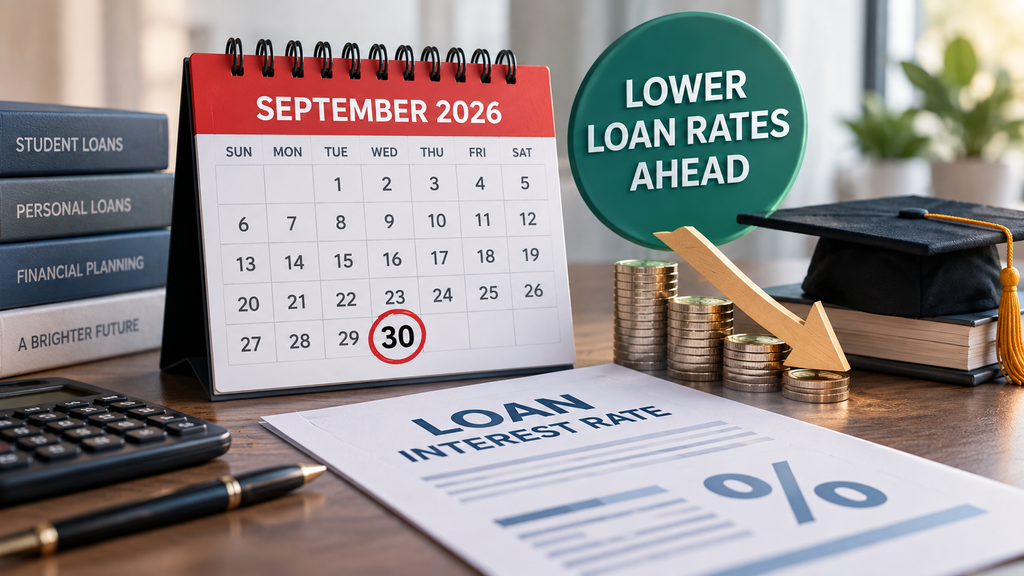
September 30, 2026 marks a crucial deadline for borrowers with eligible federal student loans.
If you sign up for automatic payments by 11:59 p.m. on that day, you could get a temporary 1% cut in your loan interest rate that lasts until June 30, 2028, according to the U.S. Department of Education.
This deadline does not cover all loan types. It specifically applies to eligible federal student loans and the related Auto Pay interest rate discount.
If you want to reduce your borrowing costs, here’s what the September 30 deadline means, who can benefit, how the interest rate cut works, and what to verify before the deadline arrives.
Understanding the September 30 Loan Interest Rate Deadline
September 30 marks the final day for qualifying federal student loan borrowers to sign up for Auto Pay and benefit from a temporary 1% reduction in their loan interest rate.
Starting July 1, 2026, the U.S. Department of Education raised the Auto Pay interest-rate discount from 0.25% to a full 1 percentage point.
Borrowers who sign up by September 30 will enjoy this temporary rate cut through June 30, 2028.
Why Is the September 30 Deadline So Important?
Reducing your loan interest rate can lower the total interest that builds up on your outstanding student loan balance.
How much you save depends on factors like your loan balance, repayment plan, and how much time remains on your loan.
For instance, if a borrower owes $30,000, the yearly interest difference between a 7% and 6% rate would be about $300, before factoring in any principal repayments.
This example is meant to illustrate potential savings and does not predict the exact amount an individual will save.
Does the September 30 Deadline Apply to Every Loan?
No. This is a crucial difference that borrowers need to be aware of.
The September 30 deadline doesn’t require refinancing personal loans, mortgages, auto loans, or private student loans by that date.
The temporary 1% interest rate reduction applies only to qualifying federal student loans with Auto Pay enrollment.
Who Is Eligible for the 1% Interest Rate Discount?
Federal student loan borrowers who sign up for Auto Pay by September 30, 2026, qualify for the temporary 1 percentage-point interest rate cut.
The Department of Education states that the enhanced reduction applies to qualifying Direct Loans issued on or after July 1, 2012.
You should verify your individual eligibility with your loan servicer.
What If You’re Already Enrolled in Auto Pay?
If you are currently signed up for Auto Pay, you typically don’t have to enroll again.
Under the updated plan, the total Auto Pay discount rises to 1 percentage point, so borrowers who previously got a 0.25% discount may now qualify for an extra 0.75% reduction.
Log into your servicer account to verify how the discount is reflected on your loans.
The Importance of Loan Interest Rates for Borrowers in 2026
Borrowing costs continue to be a key concern for many households across the U.S.
On September 16, 2026, the Federal Reserve increased the federal funds target range by 0.25 percentage points to 3.75%–4%.
Meanwhile, the Federal Reserve Bank of New York reported that total U.S. household debt hit $18.8 trillion in the second quarter of 2026.
These numbers don’t dictate the exact rate a borrower receives, as loan pricing varies across different types of loans.
Still, they explain why many people keep a close eye on their borrowing expenses.
How Does the Federal Funds Rate Affect My Loan?
The federal funds rate isn’t the interest rate applied to your personal or student loans.
Rather, it’s the rate banks charge each other for overnight loans of reserve balances.
Monetary policy shifts can affect the overall financial landscape, but their impact on a specific loan varies based on the credit type and how its interest rate is set.
This difference is key to understand when you see news about loan rates “dropping” or “increasing.”
Loan Interest Rate vs. APR: What’s the Difference?
The interest rate represents the percentage charged on the money you borrow, while APR offers a more comprehensive view of the yearly cost, including some additional fees.
When comparing personal loans, APR is especially helpful because loans with identical interest rates can vary due to different fees.
Why This Is Important When Comparing Personal Loan Offers
NerdWallet found that personal loan APRs can vary widely, typically falling between 6% and 36%, depending on the lender and borrower’s profile.
Data from September 2026 also revealed notable differences in average prequalified APRs based on credit scores and borrower profiles.
This means the APR another borrower is offered won’t necessarily match the rate you’ll qualify for.
How to Find Out Your Loan Interest Rate Before September 30
The quickest way to find out if the deadline affects you is by reviewing your federal student loan account and checking your Auto Pay enrollment.
Use these steps:
Step 1: Review Your Current Loan Interest Rate
Sign in to your federal student loan servicer’s online portal.
Note down the interest rate listed for each of your loans.
Step 2: Confirm Your Auto Pay Status
Go to the payment settings area and check if Auto Pay is currently enabled.
If you’re not signed up yet, follow the servicer’s instructions to enroll in Auto Pay.
Step 3: Confirm Your Interest Rate Discount
Check for details indicating if the Auto Pay discount is being applied to your loan.
If the details aren’t available, reach out to your loan servicer for assistance.
Step 4: Verify Your Bank Account Details
Ensure the bank account linked to Auto Pay is active and contains enough funds for scheduled payments.
Step 5: Keep a Record of Your Confirmation
Once enrolled, be sure to save your confirmation email or proof of enrollment for your records.
Keeping this confirmation can be helpful if you need to address any issues with your account later on.
Is the September 30 Deadline Relevant for Personal Loans?
No. Personal loan holders won’t automatically qualify for the 1-point interest rate cut by the September 30 deadline.
If your personal loan carries a high interest rate, there may be alternative ways to lower your borrowing expenses.
Some options to consider include:
- Evaluating different refinancing offers
- Consulting your current lender about lower rates
- Boosting your credit score before applying
- Comparing loan offers by their APR
- Shortening the loan term if you can afford it
Refinancing decisions should focus on the overall cost of the loan, not just the stated interest rate.
What Are the Consequences of Missing the September 30 Deadline?
Failing to meet this deadline doesn’t mean you lose all chances to cut your borrowing costs.
Still, you might miss out on the special temporary Auto Pay rate reduction available only through the September 30 enrollment period.
What happens if you miss the deadline:
- Review your federal student loan account.
- Reach out to your loan servicer about any available perks.
- Explore your repayment plans and options.
- Assess your other debts with high interest rates.
- Consider refinancing personal loans separately if applicable.
It’s important to separate this particular federal student loan benefit from broader options like refinancing or negotiating other debts.
Borrower’s Money Checklist for September 2026
September is a great time to take stock of your borrowing expenses.
In September, the Bureau of Labor Statistics is set to release several key economic reports, including the August jobs report on September 4, the August Consumer Price Index on September 11, and the JOLTS report on September 29.
While these reports won’t directly set your personal loan interest rate, they help provide insight into the overall economic environment.
Review Your Debts
Make a straightforward list that includes:
- Loan balance
- Loan interest rate
- APR
- Monthly payment
- Remaining term
- Potential fees
Spot Where Your Costs Might Be Highest
Start by focusing on debts that carry the steepest interest rates.
Credit cards and certain personal loans often have much higher rates than other types of consumer borrowing.
Look for Discounts You Might Qualify For
Check if your lender or loan servicer provides any perks or discounts related to:
- Enrollment in Auto Pay;
- Existing borrower relationships;
- Participation in certain repayment plans;
- Other eligible criteria.
Make sure to confirm the details directly with your loan provider.
Author’s Perspective
Understanding the September 30 deadline is important because it marks a specific chance for eligible federal student loan borrowers—not a universal cutoff for all loans nationwide.
If you qualify, reviewing your Auto Pay status before the deadline helps ensure you’re benefiting from the potential interest rate discount.
For everyone else, the takeaway is broader: avoid making borrowing choices based only on headlines about loan rates.
When evaluating debt options, consider the loan interest rate, APR, fees, monthly payment, repayment length, and total cost together.
This approach gives you a clearer understanding of what the loan truly costs and whether switching loans makes sense for your finances.
Recommended Content
Why your card’s annual fee keeps climbing
Learn what drives increases and how to calculate whether your card is still worth it.
Continue reading * You will remain on the current site